

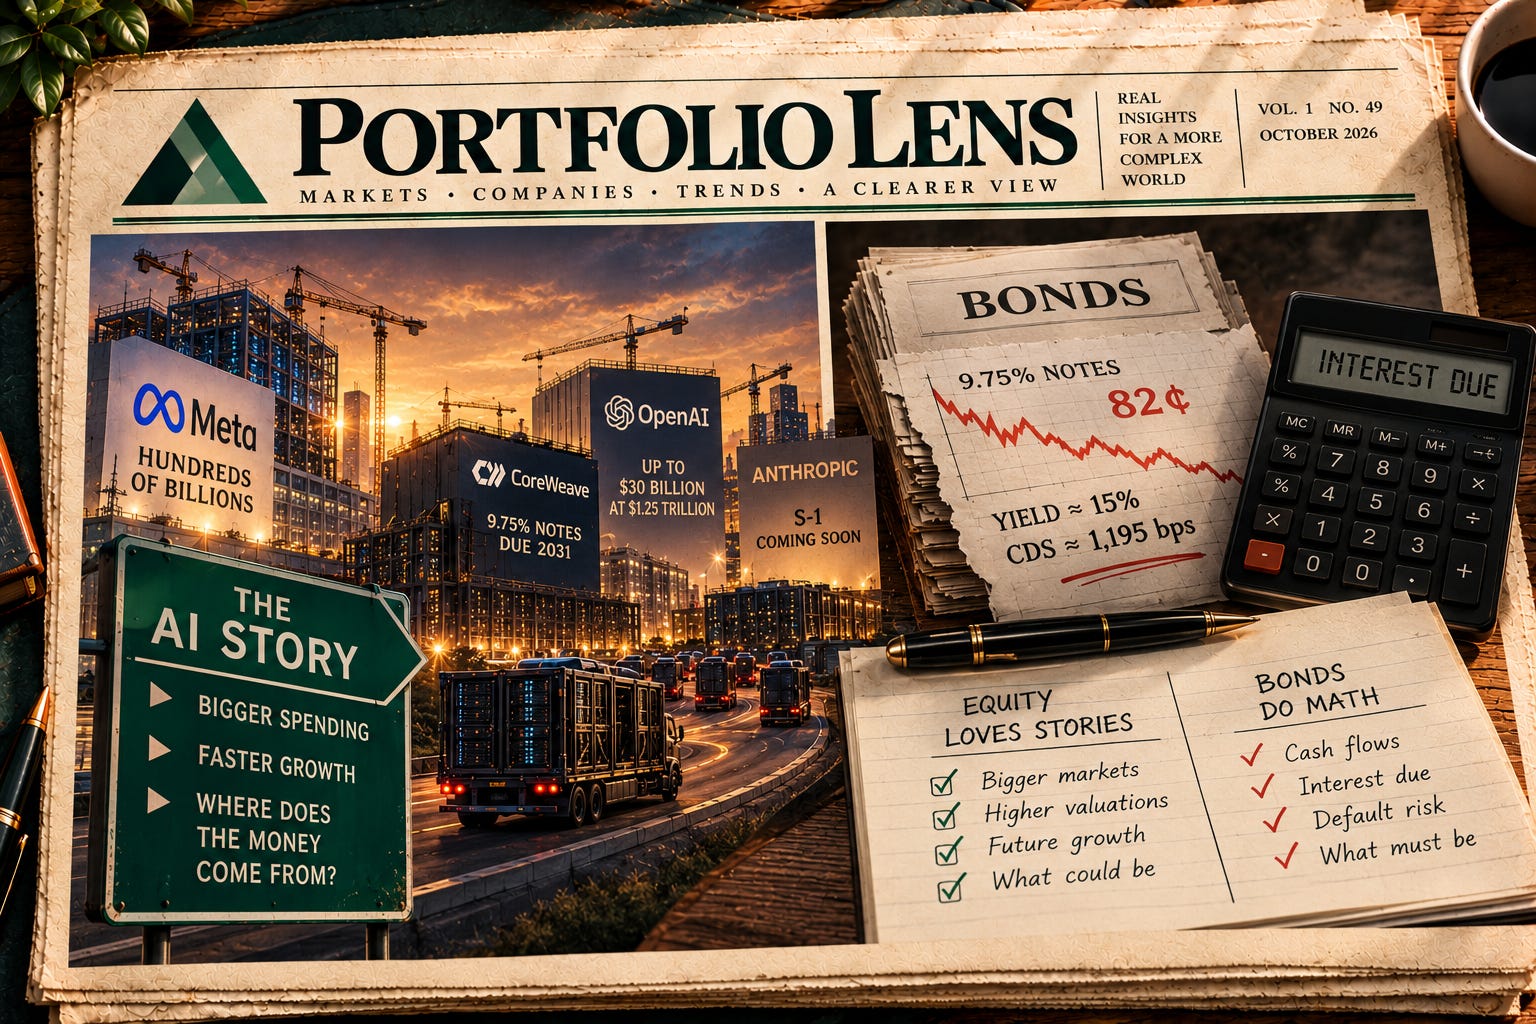
Monday October 26th, 2026
For three years, the AI story has centered around two numbers:
How much do companies spend?
How fast does revenue grow?
This week a third number made itself heard: Where does the money come from?
Two filings, one bond market and one funding round made the point in four days.
Meta: “hundreds of billions of dollars”
On October 21, Meta filed a preliminary information statement for a new class of non-voting stock. The reason sits in the background section. Management told a special committee of the board that three long-term forecast cases each “showed the Company’s need to raise hundreds of billions of dollars over a period of several years beginning as early as fall 2026.”
The same filing says Meta “anticipates needing to raise additional capital in the near term, including in the form of equity.” The committee’s banker estimated Meta could raise about $700 billion of equity over a number of years before Mark Zuckerberg’s voting power fell below 50%. The committee also weighed debt, and noted that borrowing on that scale “could have an adverse effect on the Company’s credit ratings.”
One of the most profitable companies the world has ever seen is telling its shareholders it expects to need outside money for the build-out.
CoreWeave: the bond market’s price
CoreWeave rents out AI computing capacity and has paid for its data centers largely with borrowed money. Its 9.75% notes due 2031 traded near 82 cents on the dollar in mid-October, implying a yield of about 15%, according to Bloomberg data. The notes pay 9.75% a year. At 82 cents, the market is demanding about 15% to hold them.
Its five-year credit default swaps, which work like insurance against a default, reached a record of about 1,195 basis points on October 15, according to ICE data reported by Bloomberg. S&P Global treats anything above 1,000 as a sign of distress. By the standard calculation, that price implies better-than-even odds of a default within five years. The exact figure depends on what lenders assume they would recover.
We loved Steve Eisman’s line: “Equity investors love stories. Fixed income investors care about math.”
A bondholder’s question is narrow. Does the cash arrive before the interest is due?
OpenAI: a price being negotiated
OpenAI is close to raising up to $30 billion at a $1.25 trillion valuation before the new money, led by investors from the UAE and Coatue, CNBC reported on October 22, citing people familiar with the talks. Days earlier, Reuters reported OpenAI was seeking more than $1.4 trillion. Its last round, in March, raised $122 billion at $852 billion after the money. Nothing has been announced.
Two numbers a week apart are not a contradiction. In private markets, a valuation is the price of the last deal, and this one was still being negotiated.
Anthropic: the first full set of numbers
Anthropic submitted its draft registration statement confidentially in June. As of October 25, no public S-1 is on EDGAR. When it appears, it will be the first time an AI lab of this size publishes audited financials, risk factors and major contracts in one document.
Press accounts of the confidential draft circulated all week, and they disagree on basic figures. We will not cite them until the filing is public.
Aswath Damodaran wrote this week that IPOs like this are priced, not valued: bankers set the price from the last private round and from multiples of whatever metric is in fashion. Our job is narrower. We read what the company files. Here is what we will check.
Four things to check in an AI prospectus
1. Is revenue gross or net? When a model is sold through Amazon’s, Google’s or Microsoft’s cloud, a company can book the full price the customer pays and count the cloud’s cut as a cost. That is gross. Or it can book only what it keeps, which is net. Damodaran notes that Anthropic has reported gross while OpenAI moved towards net, and that one report says net accounting would cut OpenAI’s run rate from $70 billion to $50 billion. In the revenue-recognition note, look for “principal” and “agent.” Principal means gross.
2. A run rate is not revenue. Annual recurring revenue (ARR) multiplies a recent month, week or day by twelve. No accounting rule defines it, and a company can change how it calculates it. Compare any ARR figure with the latest quarter’s reported revenue times four. The gap is growth or the choice of period.
3. Separate the cash loss from the accounting loss. A young company that raised money through convertible notes or similar instruments may have to mark them to market. When its valuation soars, so does the charge: a loss on paper with no cash leaving. Start at net loss, then go to the cash flow statement. Operating cash flow and capital spending are the cash. Stock-based compensation is non-cash but still a real cost, paid in shares.
4. Customers and commitments. Two disclosures matter. First, customer concentration: the filing should name the share of revenue from its largest customers. Second, contractual obligations: multi-year commitments to buy computing capacity, often noncancelable, which are owed whether or not revenue keeps growing. Compare them with revenue. Then note who the other side is. The same cloud companies can be a lab’s supplier, distributor, investor and competitor at once.
Who pays
AI has been an earnings story about capital spending and cloud growth. It is now also a financing story: equity at Meta, debt priced at distress levels at CoreWeave, a trillion-dollar private round at OpenAI, and a public offering at Anthropic. Each answers the same question in a different market. Who pays for the build-out, and on what terms?
We take no view on what any of these companies is worth. The day Anthropic’s filing is public, we will go through it line by line, with every number sourced to its page.
Subscribe block: If you want the filing read the day it lands, subscribe free to Portfolio Lens Research. We publish what companies file and what they promised, and we check both against what happens.
For information only. Not investment advice. Nothing in this article is a recommendation to buy, sell or hold any security.
Sources (for the post): Meta PRE 14C, Oct 21, 2026 · Meta 10-Q, Q3 2026 · CNBC, CoreWeave CDS, Oct 15 · CNBC, CoreWeave yields, Oct 21 · CNBC, OpenAI round, Oct 22 · Damodaran, "From Eyeballs to ARR", Oct 22