

Wall Street has an enduring affection for surprises, particularly those that can be explained afterward as inevitable. Our current examples:
Netflix made more profit on each dollar of revenue but spent more on content than our standards allowed.
Tesla improved its automotive margins while operating income fell by more than half.
IBM delivered four bullish results, although a favorable tax rate helped its earnings.
Meta, the world’s largest social advertising business, exceeded its own revenue forecast only to discover that a $9.89 billion legal settlement can make even a respectable quarter look dreadful.
The lesson is familiar: Corporate earnings are rarely as simple as the headlines written about them.
This is Portfolio Lens’s second attempt to impose a little discipline on the proceedings. Before Netflix, Tesla, IBM and Meta reported, we published 19 financial and operating thresholds. Eighteen could be measured: nine Bull, six Neutral and three Bear. One remained ungraded because Tesla did not disclose the necessary information. The grades are less important than the rules governing them. We do not change the thresholds after earnings, and we do not quietly discard the results that disappoint us. As our first scorecard demonstrated, accountability begins when predictions become records. The purpose is not to prove that we can see the future. It is to prevent ourselves from rewriting the past.
How We Keep Score
We published our thresholds before earnings announcement’s: Netflix on October 6, Tesla and IBM on October 7, and Meta on October 21. They are not predictions about the results. They define the performance required for a bullish, neutral or bearish assessment. We compare them with company earnings releases and SEC filings, not analyst estimates. A result at or beyond the bullish threshold earns a Bull grade; at or beyond the bearish threshold, Bear; everything between is Neutral. For costs and spending ratios, lower is better. We do not change thresholds after earnings, and measures a company does not disclose stay ungraded.
One disclosure: on the morning of October 21, before Meta reported, we moved our bearish revenue line from $63 billion to $61 billion, the bottom of Meta’s own forecast, after finding that our original draft had used outdated guidance. We grade against the line as published that morning.
The Scorecard
Netflix: More Profit per Dollar, More Spending per Show (GRADED — results Oct 20)
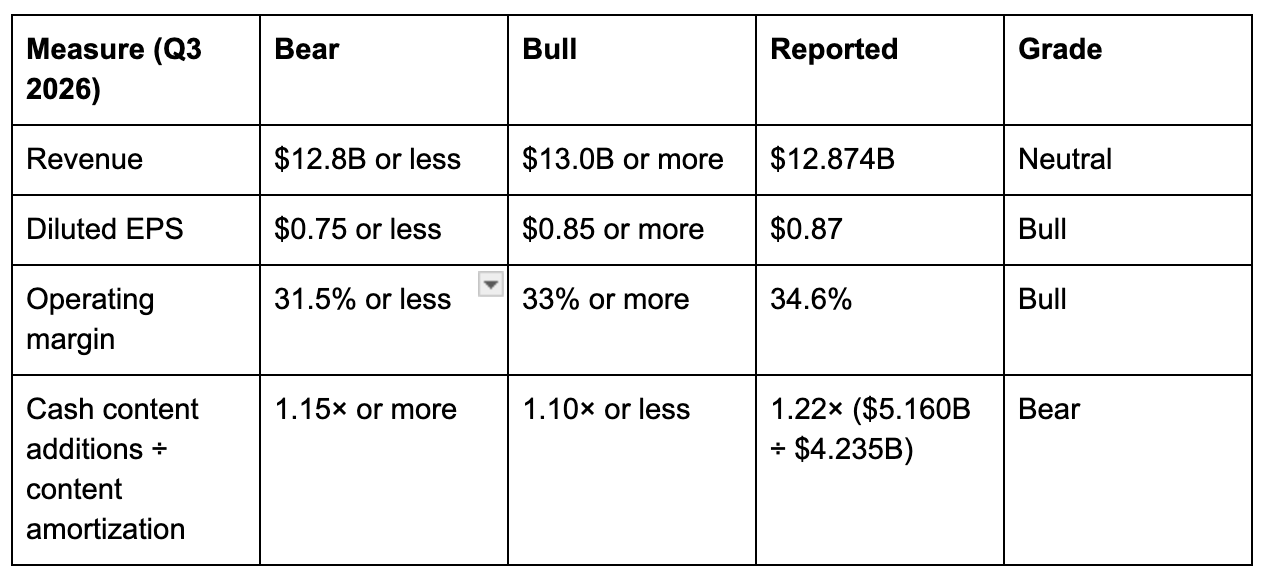
Netflix reported third-quarter revenue of $12.87 billion, up 12%, which the company described as consistent with its forecast. That landed between our lines: $13 billion or more would have been bullish, $12.8 billion or less bearish. Profitability was stronger. Operating margin reached 34.6%, up from 28.2% a year earlier and above our 33% bullish threshold, though Netflix attributed the margin’s lead over its own forecast primarily to the timing of expenses. Diluted earnings of $0.87 per share cleared our $0.85 bullish line.
The bearish result came from content spending. Netflix added $5.16 billion of content assets in cash during the quarter against $4.24 billion of content amortization, a ratio of 1.22. Our bearish threshold was 1.15, set against management’s long-term target of 1.10. Spending ahead of amortization is not necessarily a mistake; it is a bet on future programming. But it is the measure on which this quarter fell short of our standard.
The quarter’s most consequential disclosure sat outside our four measures. Netflix now expects 2026 advertising revenue of about $2.7 billion, compared with approximately $3 billion previously, citing a slower rollout of some ad product capabilities, while saying subscription revenue growth “has outperformed our expectations.” It also lowered its 2026 free cash flow forecast to about $12.0 billion from $12.5 billion, primarily because of an expected real estate transaction. Netflix finished with two Bull, one Neutral and one Bear grade.
Source: Netflix Q3 2026 shareholder letter (8-K, October 20, 2026).
Tesla: Better Margins, Flat Sales, a Robot Line That Started (GRADED — results Oct 21, 8-K filed 13:41 PT)
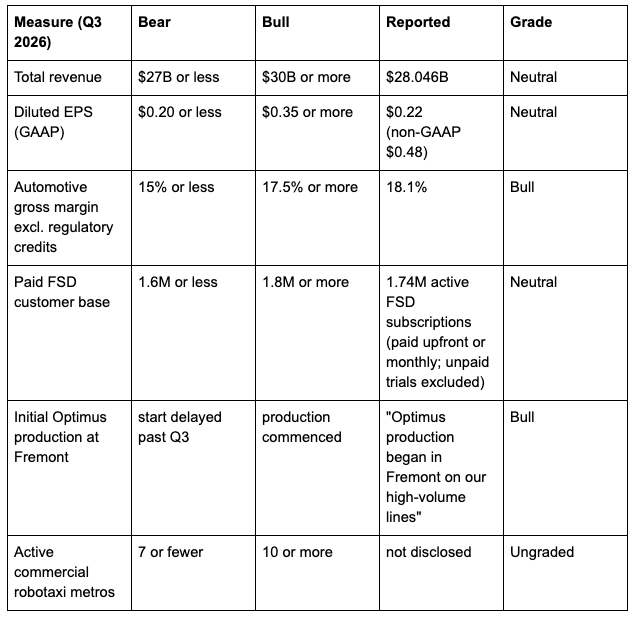
Tesla reported third-quarter revenue of $28.05 billion, roughly flat from $28.10 billion a year earlier and inside our neutral range. Deliveries fell 2% to 486,532. Tesla cited lower average selling prices, fewer regulatory credits and tariff-related refunds in its energy business, offset partly by services and higher FSD sales. Diluted earnings of $0.22 a share also landed between our lines. Our thresholds were set against GAAP earnings ($0.32 in the second quarter, $0.39 a year earlier), so the grade uses GAAP; Tesla’s non-GAAP figure, which excludes stock-based compensation, was $0.48.
The strongest result was the one we called the number to watch. Automotive gross margin excluding regulatory credits rose to 18.1% from 16.3% in the second quarter and 15.4% a year earlier, above our 17.5% bullish threshold. Operating income still fell to $718 million from $1.62 billion a year earlier. Tesla pointed to higher operating expenses for “SI” (its term for its AI work) and other research projects, and stock-based compensation, including the 2025 CEO award, partly offset by an improved vehicle region and product mix.
Tesla ended the quarter with 1.74 million active FSD subscriptions, a measure that includes upfront purchases and monthly subscriptions and leaves out unpaid trials, up from 1.48 million in June but short of our 1.8 million line. On Optimus, the company wrote that “Optimus production began in Fremont on our high-volume lines,” calling them “the first production-quality bots that we have manufactured.” Our bearish case required a delay past the third quarter; Tesla reports the start, so the measure grades Bull, though the release does not give a date. On robotaxi, Tesla began adding Cybercabs to its Austin fleet on September 3 and reported nearly two million cumulative unsupervised miles, but it did not state how many metropolitan markets are active. As with Micron in Scorecard #1, a measure the company does not disclose stays ungraded. We will check the transcript of Tesla’s earnings call; if management states the number there, we will report it in our next scorecard. Tesla finished with two Bull, three Neutral and one ungraded measure.
Source: Tesla Q3 2026 Update (8-K Ex. 99.1, filed October 21, 2026).
IBM: Faster Growth, Wider Margins, Cash Still Catching Up (GRADED — results Oct 21, 8-K filed 13:19 PT)
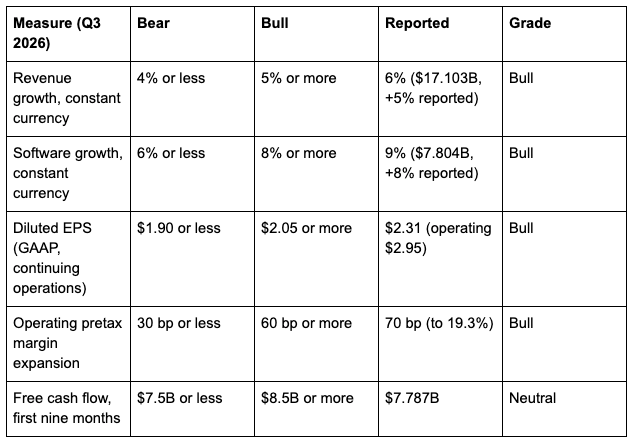
IBM reported third-quarter revenue of $17.10 billion, up 5%, or 6% at constant currency, above our 5% bullish threshold. Software, the segment we treated as the test, grew 9% at constant currency to $7.80 billion and also cleared its 8% line. Within it, Data grew 19% and Red Hat 11%, while Automation fell 3%; Transaction Processing, which our bearish case expected to stay negative, rose 9%. Infrastructure’s mix was uneven: Distributed Infrastructure grew 31% while IBM Z fell 20%. Consulting was flat.
Operating pretax margin widened 70 basis points to 19.3%, above our 60 basis-point bullish line and well ahead of management’s own guide of an expansion similar to the second quarter’s 30 basis points. Diluted earnings from continuing operations were $2.31 a share, above our $2.05 line, against $1.84 a year earlier. That figure deserves the same qualification Costco’s did in Scorecard #1. GAAP pretax income rose only 3%; a tax rate of 11.9%, against 28.2% a year earlier, did most of the work in lifting net income 26%. IBM’s operating (non-GAAP) earnings of $2.95 a share, up 11%, would also have cleared the line, so the grade does not depend on the tax rate, but the size of the gain does.
Free cash flow was the exception. IBM generated $3.03 billion in the quarter and $7.79 billion over nine months, up $0.6 billion, inside our neutral range. Our bullish line required at least $3.7 billion in the third quarter. IBM raised its full-year outlook to free cash flow growth of “more than $1 billion year-over-year” and kept its constant-currency revenue growth forecast at four to five percent. Debt rose $2.6 billion this year to $63.8 billion after $11.4 billion of acquisitions. IBM finished with four Bull grades and one Neutral.
Source: IBM Q3 2026 earnings release (8-K Ex. 99.1 and 99.2, filed October 21, 2026).
Meta: Above Its Forecast, Below Our Line, and a $9.9 Billion Settlement (GRADED — results Oct 21, 8-K filed 13:03 PT)
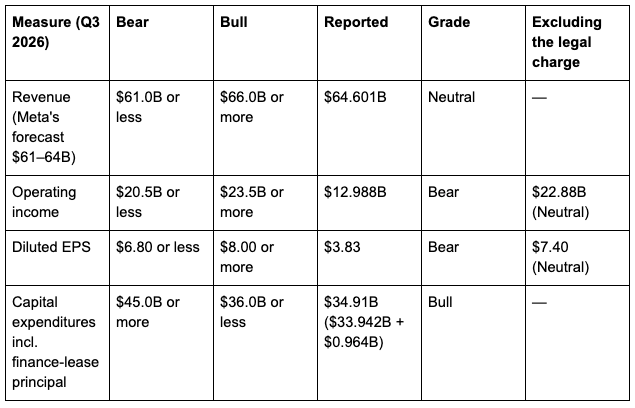
Meta reported third-quarter revenue of $64.60 billion, up 26%, above the top of its own $61–64 billion forecast but short of our $66 billion bullish threshold. Ad impressions rose 10% and the average price per ad 14%. Revenue grades Neutral.
The profit lines turned on one item. In August, Meta agreed with 52 state attorneys general to resolve litigation over teen mental health and social media, with payments of up to about $18.59 billion; the third quarter carries a $9.89 billion charge for it. Reported operating income fell 37% to $12.99 billion and diluted earnings were $3.83 a share, both below our bearish lines of $20.5 billion and $6.80. Our thresholds did not say whether they included or excluded one-time items, so, as in Scorecard #1, the official grades follow the reported numbers: two Bears. Excluding the charge, Meta says operating income would have been $22.88 billion and earnings $7.40 a share. Both would have landed in our neutral range, below the bullish lines. On that adjusted basis operating income rose about 11% from $20.54 billion a year earlier, while costs excluding the charge rose about 36%, to $41.72 billion.
Capital spending was the one bullish result. Purchases of property and equipment plus finance-lease principal came to $34.91 billion, below our $36 billion threshold. Meta narrowed its full-year range to $135–145 billion, raising the bottom from $130 billion. With $85.82 billion spent through September, that implies $49–59 billion in the fourth quarter alone, well above any quarter so far. Our low third-quarter figure may say more about timing than discipline. Free cash flow was negative $2.12 billion.
The full-year promise survives only in adjusted form. “Excluding the third quarter legal charge, we continue to expect 2026 operating income to be above 2025 operating income.” Through nine months Meta has earned $54.64 billion, or $64.53 billion before the charge; beating 2025’s $83.28 billion takes about $18.75 billion in the fourth quarter on that basis, and $28.64 billion on a reported basis. Meta raised its 2026 expense outlook to $175–179 billion to include the charge and guided fourth-quarter revenue to $73–76 billion. It also announced a new non-voting Class C share, to be distributed one for one in January 2027, which Meta says gives it a new class of stock for capital raising, employee compensation and acquisitions. Meta finished with one Bull, one Neutral and two Bear grades; excluding the charge, one Bull and three Neutral.
Source: Meta Q3 2026 earnings release (8-K Ex. 99.1, filed October 21, 2026).
What We Learned
The second scorecard tested the changes we promised after the first, and showed where they were not yet enough. We will make four more:
Say whether a line includes one-time items. Scorecard #1 promised this after Costco; our Meta lines did not say it. Meta’s settlement charge turned two neutral results into Bear grades. The rule held, and the grades stand, but a reader should not need the rulebook to know which number we meant. Every earnings line will now say “reported” or “excluding”.
Use the latest guidance. Our first Meta draft relied on guidance Meta had already replaced in July. We caught it on the morning of the report and moved one line before the results, and we have disclosed that above. Every preview now checks the company’s most recent earnings release for guidance before it is published.
Measure what the company reports. Tesla did not say how many cities its robotaxi service operates in, so one of our six lines could not be graded, just as Micron’s customer-agreement measure could not be graded last time. A threshold is only as useful as the disclosure behind it.
Look past the headline. Netflix’s content spending graded Bear in a quarter when its operating margin cleared our bullish line. IBM’s earnings beat our line on a lower tax rate as much as on its operations. Tesla’s car margins recovered while its operating income fell by more than half. Each total told a different story from the measure beneath it.
The same limit applies as before. Strong results do not make a stock a good investment, and weak ones do not make it a poor one. Our scorecard measures business performance against standards published in advance. Valuation and future returns are separate questions.
The Next Scorecards
Coca-Cola reports on October 27. Microsoft and Alphabet report on October 28, and Amazon on October 29. Each will receive the same treatment: published thresholds, reported results and an accounting of what we got right or wrong.
Two scorecards are not a track record, but they are the beginning of one. The first taught us to account for guidance and one-time items. The second showed that writing a rule down is not the same as applying it to every line. The grades this week matter less than the fact that they could not be changed after the results were known. We intend to keep publishing the numbers first, measuring the results afterward and leaving the record intact, including the lines we wish we had written differently.
About Portfolio Lens · Subscribe line · “Thresholds first. Grades later. Misses included.” · getportfoliolens.com For information only. Not investment advice. Nothing in this article is a recommendation to buy, sell or hold any security.
Locking thresholds before the print and publishing the one you couldn't grade is the part I rarely see. A parallel check we ran on options-implied moves: last week's five reports (NFLX, NEE, IBM, LRCX, TSLA) each had a stored at-the-money straddle range, and four of the five finished inside it, with LRCX at -11.8% the miss. The caveat we keep stating is that for some records we can't prove the capture came before the release, so we label 'recorded before' and 'reconstructed after' separately instead of counting both. Did you decide in advance how to handle a guidance change on the morning of the report, like your Meta revenue line, or was that a one-off call? (Disclosure: I work on an options-data app; no link here.)