

BlackBerry is a company that always gives me a sense of nostalgia. I have many happy memories of discussing it with friends in Toronto in the early aughts. Whenever I think about it, it takes me back to those days. They’re very happy memories and, for my Canadian friends, very profitable times. Today, I wonder if Blackberry can continue their climb back in recovery.
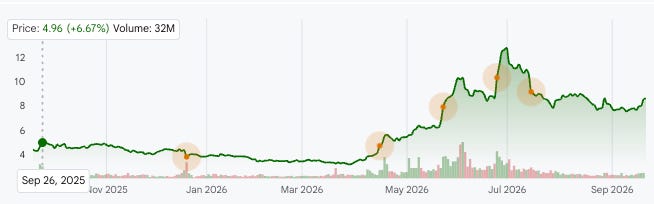
Bull Case
For BlackBerry to continue to climb and meet their bullish estimates, they would need to exceed 148 million in revenue and adjusted EBITDA of 30 million or more. Equally, non-automotive adoption needs to outpace seasonal expectations. These would be key points:
Consolidated revenue: at or above $148.0 million for Q2 FY2027 [transcript:FY2027-Q1].
Consolidated adjusted EBITDA: at or above $30.0 million for Q2 FY2027 [transcript:FY2027-Q1].
Non-GAAP adjusted basic EPS: at or above $0.04 per share for Q2 FY2027 [transcript:FY2027-Q1].
Full-year FY2027 consolidated revenue guidance: raised above the current $594.0 million to $621.0 million range [transcript:FY2027-Q1].
Bear Case
The bear case will be the driver if consolidated revenue falls below $137 million, adjusted EBITDA lands at or below $20 million or secure communication churn worsens. For this to be true, we would expect to see the following:
Consolidated revenue: at or below $137.0 million for Q2 FY2027 [transcript:FY2027-Q1].
Secure Communications segment revenue: at or below $57.0 million for Q2 FY2027 [transcript:FY2027-Q1].
Consolidated adjusted EBITDA: at or below $20.0 million for Q2 FY2027 [transcript:FY2027-Q1].
Consolidated operating cash flow: at or below $0.0 million (operating cash outflow) for Q2 FY2027 [transcript:FY2027-Q1].
Why this Event Matters
The September 24, 2026 earnings release for the second quarter of fiscal 2027 will test two core operational transitions that the prior quarter left unsettled: the normalization of the Secure Communications revenue run-rate following a lump-sum contract benefit, and the execution cadence of QNX toward its upgraded full-year targets. (Note: The transcript excerpts for the FY2027 Q1 and FY2026 Q2 earnings calls were truncated in the provided records, though initial guidance commentary and quarterly financial statements were accessible via the Q1 FY2027 10-Q and compiled financial tables).
First, the release will settle whether the Secure Communications division can establish a stable, profitable revenue floor in the absence of one-off contract windfalls. In Q1 FY2027, the segment generated $74 million in revenue—growing 24% year-over-year—bolstered by upfront revenue recognition from an expansion and multi-year contract extension with Shared Services Canada [transcript:FY2027-Q1]. Because annual recurring revenue (ARR) stood at $220 million with a dollar-based net retention rate of 92%, management guided Q2 Secure Communications revenue downward to between $57 million and $63 million and adjusted EBITDA to between $5 million and $10 million, reiterating that large government digital-sovereignty deployments create quarterly lumpiness [transcript:FY2027-Q1]. Q2 is the first reporting period to prove whether baseline demand and reduced churn can support management’s full-year segment revenue growth target of 4% to 8% ($270 million to $280 million) without relying on immediate renewals [transcript:FY2026-Q4, transcript:FY2027-Q1].
Second, the event serves as a milestone for QNX’s high-margin momentum and its emerging platform expansion. QNX delivered $72 million of revenue in Q1 FY2027 (up 26% year-over-year) with an 86% gross margin, lifted by development license revenue reaching an eight-quarter peak [transcript:FY2027-Q1]. For Q2, management guided QNX revenue to $70 million–$75 million and adjusted EBITDA to $16 million–$21 million, within a raised full-year segment revenue outlook of $295 million to $312 million [transcript:FY2027-Q1]. Crucially, management previously committed to securing the first commercial design win for Alloy Kore—its pre-integrated middleware platform developed with Vector Informatik—during fiscal 2027 to drive multiples of average selling price (ASP) expansion [transcript:FY2026-Q4, transcript:FY2027-Q1].
At the consolidated level, Q2 results will verify whether operating leverage can sustain the targeted 90% flow-through of incremental revenue to adjusted EBITDA. BlackBerry guided total Q2 revenue to $137 million–$148 million, adjusted EBITDA to $20 million–$30 million, adjusted EPS to $0.03–$0.04, and operating cash flow to between breakeven and $10 million [transcript:FY2027-Q1], following GAAP net income of $8.5 million in Q1 [0001070235-26-000076, financials:FY2027-Q1]. Meeting these targets will establish whether the company’s multi-quarter return to GAAP profitability and positive cash generation remains durable as seasonal software delivery and government procurement cycles evolve.