

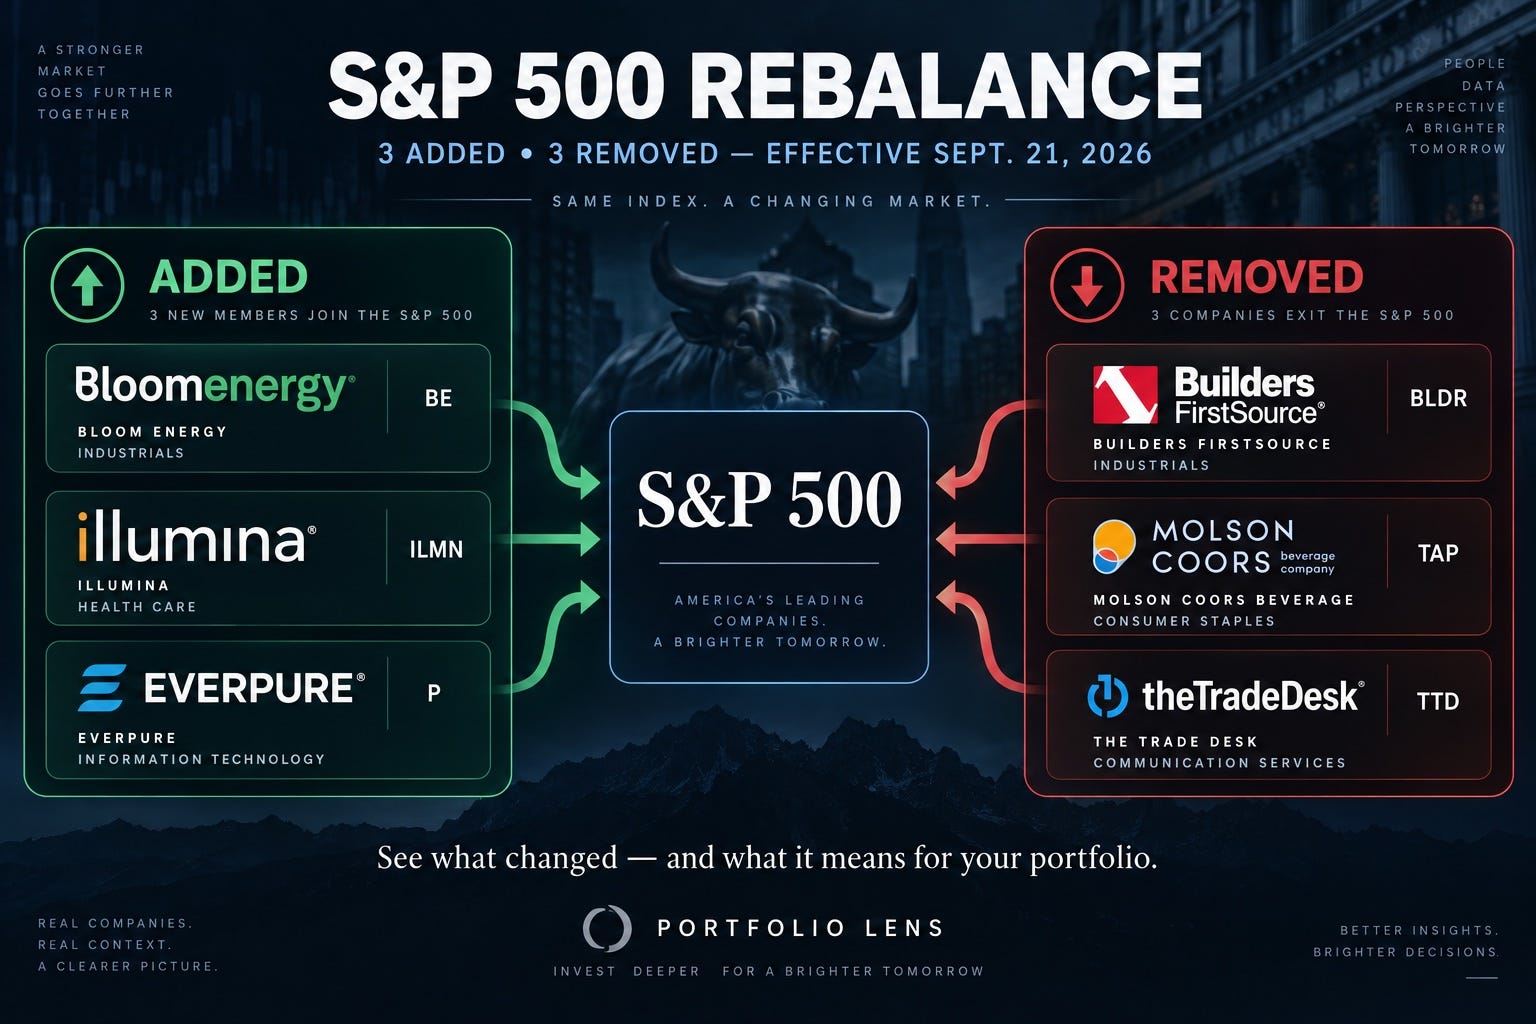
Three stocks were added to the S&P 500 today (Bloom Energy, Illumina and Everpure) three were taken out (Builders FirstSource, Molson Coors and theTradeDesk). I just want to look at Everpure today and look at what makes this company so bullish and what’s going to be important for this company to execute on in the current quarter.
Bull Case
The bull case turns on the fact that Q3 FY 2027 revenues are at or above $1.3 billion, and the product’s gross margin expands to or above 69%. This should come from accelerated hyperscale shipments. For these to be true, we need to see the following:
Total revenue: at or above $1.300 billion for Q3 FY2027 (year-over-year growth of 34.8% or more from $964.5 million in Q3 FY2026)
Product gross margin: at or above 69.0% for Q3 FY2027, driven by high-margin hyperscale shipments yielding 75% to 85% margins
Non-GAAP operating profit: at or above $255 million for Q3 FY2027 (surpassing the $230 million record achieved in Q2 FY2027)
Diluted earnings per share (GAAP): at or above $0.26 for Q3 FY2027
Bear Concerns
The bear case turns on Q3 FY 2027 revenue landing at or below $1.2 billion, with product gross margin stalling out at or staying below 66.5% as hyperscale deliveries slip. For this to be true, we would expect to see the following:
Total revenue: at or below $1.200 billion for Q3 FY2027 (year-over-year growth of 24.4% or less from $964.5 million in Q3 FY2026)
Product gross margin: at or below 66.5% for Q3 FY2027, as component inflation outpaces pricing and hyperscale deliveries fail to ramp
Non-GAAP operating profit: at or below $215 million for Q3 FY2027
Diluted earnings per share (GAAP): at or below $0.18 for Q3 FY2027
Why this Event Matters
The December 1, 2026 earnings release for the third quarter of fiscal 2027 settles two core commitments management made across earlier calls: the timing of the hyperscaler revenue ramp and the gross margin inflection promised for the second half of the year.
Throughout the preceding three quarters, management consistently deferred expectations for hyperscaler contribution into the back half of fiscal 2027 [transcript:FY2026-Q4, transcript:FY2027-Q1, transcript:FY2027-Q2]. In both the first and second quarters of fiscal 2027, management explicitly characterized hyperscale revenue contribution as “minimal” [transcript:FY2027-Q1, transcript:FY2027-Q2], reiterating that contracted customer delivery schedules concentrated shipments into the third and fourth quarters [transcript:FY2026-Q4, transcript:FY2027-Q1, transcript:FY2027-Q2]. Q3 FY2027 is the first period where this committed order volume must appear directly in reported product revenue rather than remaining a multi-quarter forward commitment.
Directly tied to the hyperscale delivery timing is product gross margin recovery. Component cost inflation compressed product gross margin to 65.5% in Q1 FY2027 [transcript:FY2027-Q1] and 66.2% in Q2 FY2027 [transcript:FY2027-Q2], sitting at the lower boundary of management’s traditional 65% to 70% range [transcript:FY2026-Q4, transcript:FY2027-Q1, transcript:FY2027-Q2]. Management established that under its standardized hyperscale delivery model—where Everpure supplies hardware and software components while the customer procures NAND separately—hyperscale revenue yields gross margins between 75% and 85% [transcript:FY2026-Q4, transcript:FY2027-Q2]. Management specifically guided that these accretive shipments in Q3 and Q4 would begin lifting aggregate product gross margins [transcript:FY2027-Q1, transcript:FY2027-Q2]. The Q3 report tests whether that margin expansion materializes amid continued component pricing volatility.
The release will also test whether the accelerated top-line growth seen in the first half of the year—revenue expanded 35% year-over-year to $1.053 billion in Q1 [transcript:FY2027-Q1] and 38% to $1.186 billion in Q2 [transcript:FY2027-Q2]—reflected durable market share gains or transient customer pull-ins. In Q1, management estimated that price increases and customer purchasing ahead of further cost hikes accounted for nearly one-third of year-over-year revenue growth [transcript:FY2027-Q1]. Q3 will reveal whether underlying enterprise demand and Evergreen//One consumption momentum (which achieved an annualized total contract value run rate above $1.0 billion in Q2 [transcript:FY2027-Q2]) remain resilient once pull-in activity fades.
Finally, the report will show whether cash generation stabilizes following balance sheet pressures in Q2 FY2027, when operating cash flow dropped to -$136.3 million and free cash flow stood at -$237.6 million, reducing cash and short-term investments to $1.008 billion [financials:FY2027-Q2].