

I've looked at clouds from both sides, now
From up and down, and still somehow
It's cloud illusions, I recall
I really don't know clouds at all - Joni Mitchell
Dreams and Reality
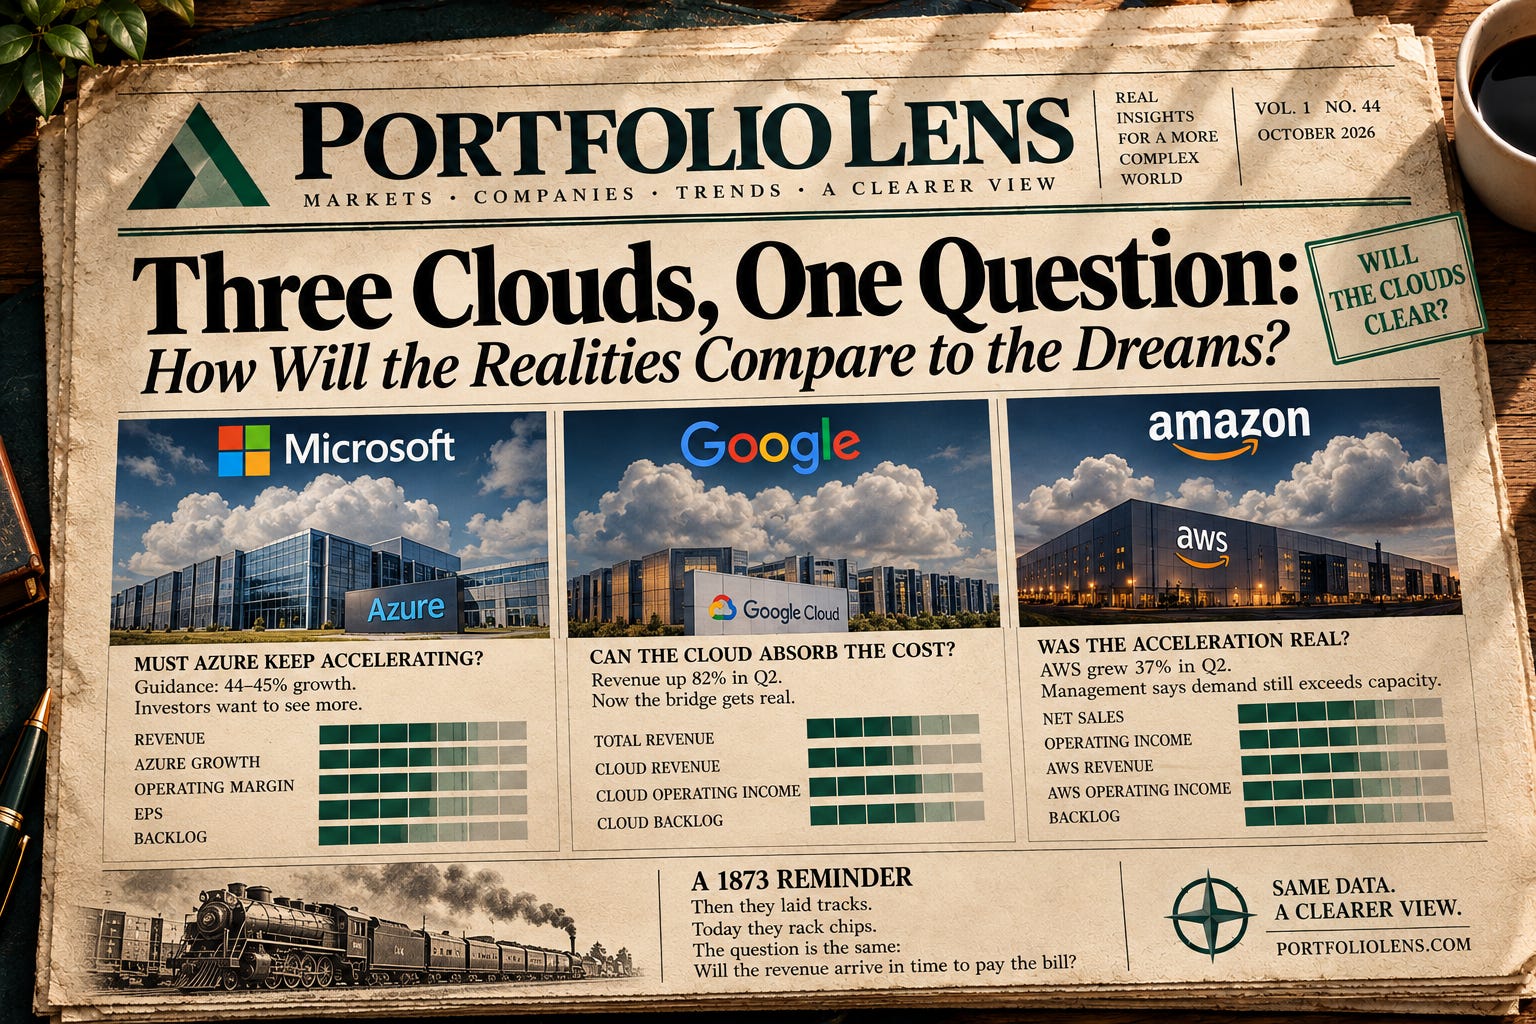
Every adventure has two perspectives: the dream people have before it begins, and the reality, realized when the bill arrives. The nineteenth-century railroads produced plenty of the first and, in time, a sobering quantity of the second. Microsoft’s Satya Nadella had that in mind when asked about AI data center overbuilding, he said “all of us are reading this 1873 as the book to be read.” That was the year of a famous railroad panic. Today’s builders are not laying track, but racking chips, and each plans to spend roughly $175 billion to $220 billion in 2026. The question is: whether the revenue arrives in time to pay the bill?
Next week Microsoft, Alphabet and Amazon all report within about 24 hours. Microsoft must show Azure beating its guidance of 44–45%. Alphabet must show that a cloud business growing 82% and can absorb the cost of rented capacity. Amazon must show that AWS’s acceleration to 37% was a trend, not a quarter. We find 15 thresholds to monitor in their disclosed figures. Where management guides, Bull cases require beating the top of the range; the top itself grades as Neutral. Ideas in the air are cheap. Forecasts written down are commitments.
Microsoft (reports Wednesday, October 28, after the close)
Fiscal 2027 first quarter, the first under new segments.
Bull Case
Total revenue: At or above $90.96B (guidance $89.85–90.95B).
Agents and Infra revenue: At or above $75.76B (guidance $75.15–75.75B).
Azure growth, constant currency: At or above 46% (guidance 44–45%).
Operating margin: At or above 49.1% (implied by guidance: 48.0–49.0%; our arithmetic).
Non-GAAP diluted EPS: At or above $4.79 (implied by guidance: $4.63–4.78; our estimate).
Commercial RPO (backlog): At or above $720B.
Bear Case
Total revenue: At or below $89.84B.
Agents and Infra revenue: At or below $75.14B.
Azure growth, constant currency: At or below 43%.
Operating margin: At or below 47.9%.
Non-GAAP diluted EPS: At or below $4.62.
Commercial RPO (backlog): At or below $678B (no growth from June 30).
Why This Release Matters
Microsoft has beaten the top of its revenue and Azure guidance in each of the last two quarters (June revenue: $90.0 billion against $86.7–87.8 billion). Azure is graded on September’s narrower definition. The CFO said Microsoft continues “to expect H1 growth to accelerate.” Non-GAAP EPS excludes only OpenAI; June’s $3.2 billion Anthropic gain stayed in. Capex is tracked, not graded.
Alphabet (reports Wednesday, October 28)
Third quarter. Alphabet gives no quarterly guidance, so these thresholds are our judgment, anchored to its own trend.
Bull Case
Total revenue: At or above $127.0B (24% growth, as in Q2).
Google Cloud revenue: At or above $29.0B ($24.8B in Q2).
Google Cloud operating income: At or above $9.5B ($8.8B in Q2).
Google Cloud backlog: At or above $565B.
Bear Case
Total revenue: At or below $122.8B (about 20% growth).
Google Cloud revenue: At or below $26.5B.
Google Cloud operating income: At or below $8.0B.
Google Cloud backlog: At or below $513.9B (no growth).
Why This Release Matters
Alphabet’s second quarter held two kinds of good news: Google Cloud revenue rose 82% at a 35.6% operating margin, and equity-securities gains, primarily SpaceX and a private company, added $6.26 to diluted EPS of $9.11. We therefore grade the cloud business, not EPS. Management plans to “expand the use of third-party capacity in Q3 as a bridging strategy.” This release shows what the bridge costs. Capex is tracked, not graded.
Amazon (reports Thursday, October 29)
Third quarter. Amazon guides only net sales and operating income.
Bull Case
Net sales: At or above $202.1B (guidance $197.0–202.0B).
Operating income: At or above $26.6B (guidance $22.5–26.5B).
AWS net sales: At or above $46.2B (40% growth).
AWS operating income: At or above $18.0B ($16.6B in Q2).
Backlog (remaining performance obligations): At or above $540B.
Bear Case
Net sales: At or below $196.9B.
Operating income: At or below $22.4B.
AWS net sales: At or below $44.6B (35% growth).
AWS operating income: At or below $16.0B.
Backlog: At or below $496B (no growth).
Why This Release Matters
Amazon beat the top of both guided ranges in both quarters so far this year. EPS is not graded: second-quarter non-operating income of $53.4 billion, “primarily from our investments in Anthropic,” exceeded operating income of $27.5 billion. Management raised its 2026 cash capex plan to about $220 billion, yet said capacity would still fall short of 2026 demand. Capex is tracked, not graded. The backlog grade follows the 10-Q.
How We’ll Grade This
The rules are those of Scorecard #1. Thresholds are not predictions. We grade against company releases and SEC filings, not analyst estimates, and never move a threshold afterward. Results between Bull and Bear are Neutral. Scorecard #3 grades Microsoft and Alphabet on October 30; Scorecard #4 grades Amazon on November 6.
The Realities Yet to Come
The dreams prospectus has been written three times, in three dialects: Microsoft in guidance ranges, Alphabet in backlog, Amazon in two lines and a promise. The audit will be the revenue that arrives, the margins that survive depreciation and the backlog that converts. The builders of 1873 did not lack confidence. They lacked an early, honest accounting. Spending is a promise. Revenue is the evidence.
Sources
Microsoft
FY27 Q1 results date and webcast time (Oct 7, 2026): Microsoft Source
FY26 Q4 earnings release (Jul 29, 2026): EDGAR 8-K Ex. 99.1
FY26 Q4 earnings call transcript (Jul 29, 2026): Microsoft IR
FY27 segments and FY27 Q1 adjusted outlook (8-K, Sep 2, 2026): EDGAR
FY26 Q3 earnings release and call (Apr 29, 2026): EDGAR 8-K Ex. 99.1 · call transcript
FY26 Q2 earnings call transcript, Q3 outlook (Jan 28, 2026): Microsoft IR
FY26 Q1 earnings release (Oct 29, 2025): EDGAR
Alphabet
Q2 2026 earnings release (Jul 22, 2026): EDGAR
Q2 2026 earnings call: Alphabet IR
Q2 2026 Form 10-Q (revenue backlog): EDGAR
Q3 2025 earnings release: EDGAR
Q3 2026 call date (Oct 28, 2026): Alphabet IR
Amazon
Q2 2026 earnings release, Q3 guidance (Jul 30, 2026): EDGAR
Q2 2026 Form 10-Q (performance obligations): EDGAR
Q1 2026 earnings release, Q2 guidance: EDGAR
Q4 2025 earnings release, Q1 guidance: EDGAR
Q3 2025 earnings release: EDGAR
Q2 2026 earnings call (Jul 30, 2026): audio at Amazon IR
Q3 2026 call date (Oct 29, 2026): Amazon IR
For information only. Not investment advice. Nothing in this article is a recommendation to buy, sell or hold any security.