

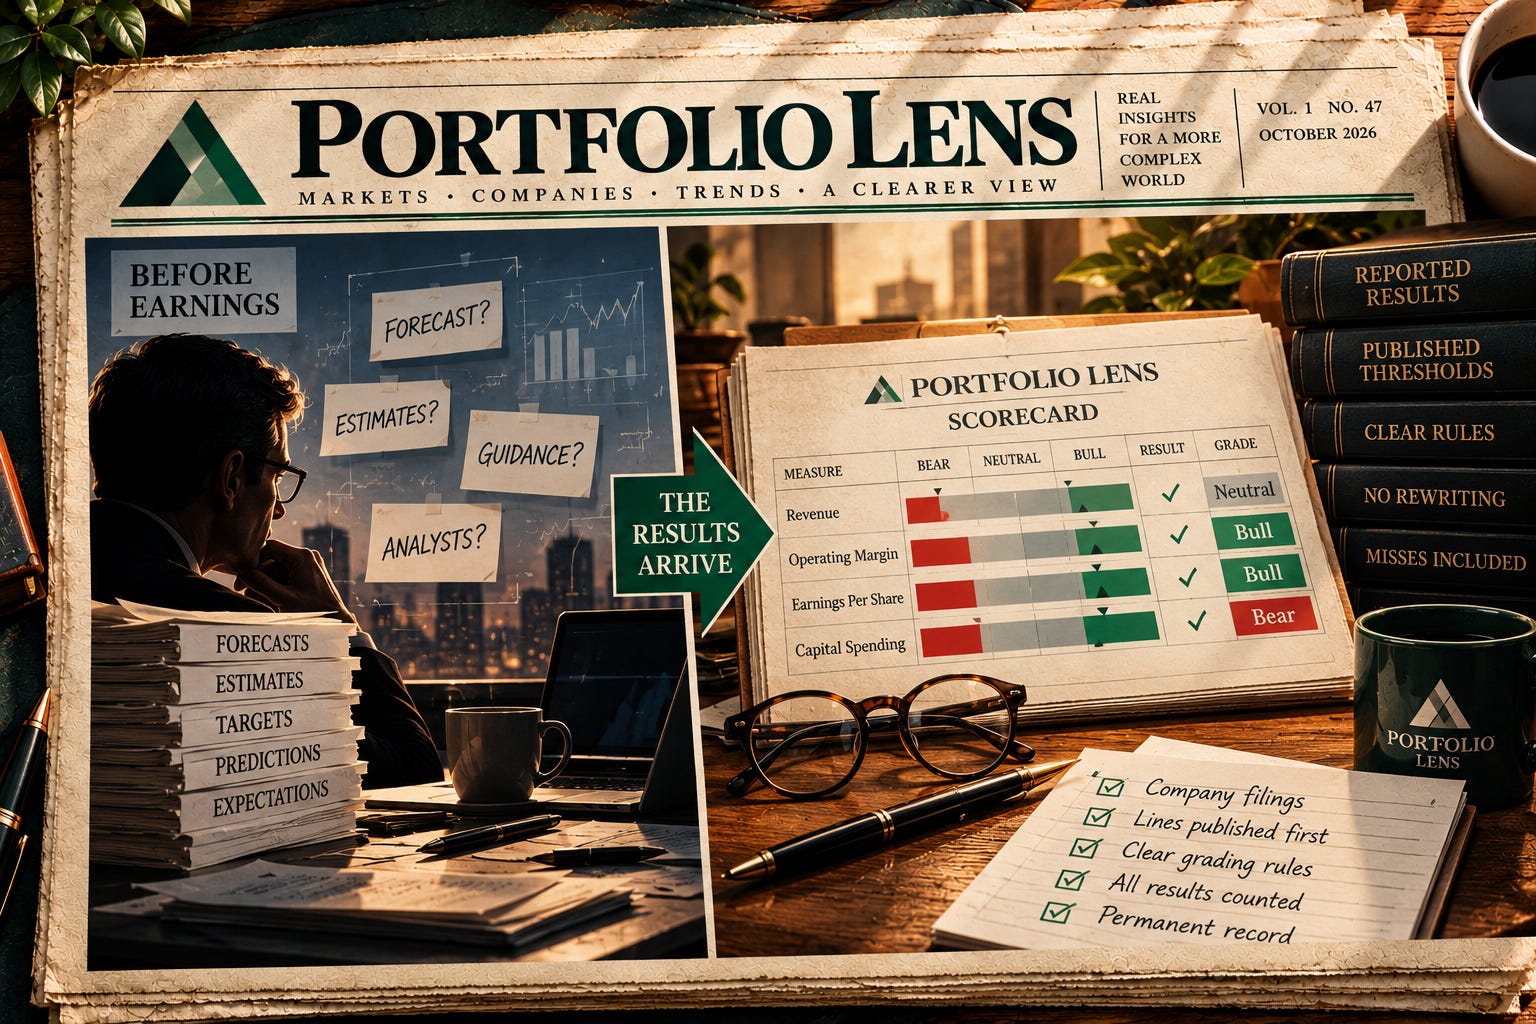
Wall Street has never suffered from a shortage of confident explanations. Before earnings, analysts offer forecasts and predictions. Afterward, they explain why the results were inevitable, even when they were not. Hindsight is a remarkable financial instrument: It requires no capital, carries no risk and produces an impressive results with certainty. The difficulty is remembering what was said before the numbers arrived. Markets have long memories for profits and surprisingly short ones for predictions.
At Portfolio Lens, we propose a modest remedy: Publish the scorecard first. Before a company reports, we publish what would constitute a strong, ordinary or weak quarter. Afterward, we compare our published scorecard with the actual results. We do not revise the numbers to accommodate inconvenient facts or numbers. This exercise is not designed to demonstrate clairvoyance. It is intended to bring accountability. Why do we write scorecards? Not to prove we can see the future, but to prevent ourselves from rewriting the past.
What Is a Line?
A line is a performance threshold, not a prediction.
Before earnings, we publish two thresholds for each measure we track, such as revenue, operating margin or capital spending.
Each result receives one of three grades:
Bull: The result meets or exceeds our strong-performance threshold.
Neutral: The result falls between our strong and weak thresholds.
Bear: The result meets or falls below our weak-performance threshold.
For costs and spending, lower figures generally represent better results.
These thresholds establish our standards before earnings. They do not change afterward.
How We Grade
We follow five rules.
1. Company numbers come first. We use earnings releases and SEC filings, not Wall Street analyst estimates.
2. The accounting basis is clear. Each earnings threshold states whether it uses reported figures or excludes specified one-time items. If no adjustment is stated, reported figures determine the grade.
3. Missing information stays missing. If a company does not disclose a measure, we mark it Ungraded. We do not invent a result.
4. Published thresholds remain on the record. We never change a threshold after results become known. Any revision made before earnings is disclosed.
5. Every result counts. We publish all grades, including those that challenge our original assessment. We explain material differences between reported results and underlying performance.
What a Grade Does Not Mean
A Bull grade does not mean a stock is a good investment. A Bear grade does not mean investors should sell.
A company can deliver excellent results while its shares remain expensive. Another can report disappointing earnings when its stock price already reflects worse expectations.
Business performance and investment value are different questions. Our scorecards measure the first, not the second.
The Record So Far
Our first two scorecards covered seven companies and 33 published measures. Of those, 31 could be graded.
Scorecard #1: Costco, Micron and Nike
Thirteen measures were graded: seven Bull, five Neutral and one Bear. One remained Ungraded.
Costco’s one-time tariff refund changed the interpretation of its earnings result. Micron did not disclose a measure we selected. Both findings helped us improve our methodology.
Scorecard #2: Netflix, Tesla, IBM and Meta
Eighteen measures were graded: nine Bull, six Neutral and three Bear. One remained Ungraded.
Netflix exceeded our profitability thresholds but missed our content-spending standard. Tesla improved automotive margins while operating income declined. IBM’s earnings benefited from a lower tax rate. Meta exceeded its revenue forecast, but a legal settlement pushed two reported earnings measures into Bear territory.
We retained every grade and explained the underlying results.
A Record Worth Keeping
Two scorecards do not establish a track record, they are a beginning.
As the record grows, readers can compare our original thresholds with reported results and judge whether our standards were useful.
We expect to make mistakes. We intend to document them.
The financial world has no shortage of predictions. What it lacks is an equally enthusiastic accounting of their consequences.
Scorecards and lines first. Grades later. Misses included.
About Portfolio Lens
Portfolio Lens analyzes earnings reports, SEC filings and management statements to identify changes in corporate performance.
Explore our research at getportfoliolens.com.
For information only. Not investment advice. Nothing here is a recommendation to buy, sell or hold any security.